Best Asset Finance Broker in Australia: What To Look For
Buying a truck, a machine or a full fit-out is a different conversation from buying a building, and it needs a different broker. We arrange commercial property finance, not asset finance, so this guide is about what separates a good asset finance broker from an average one.
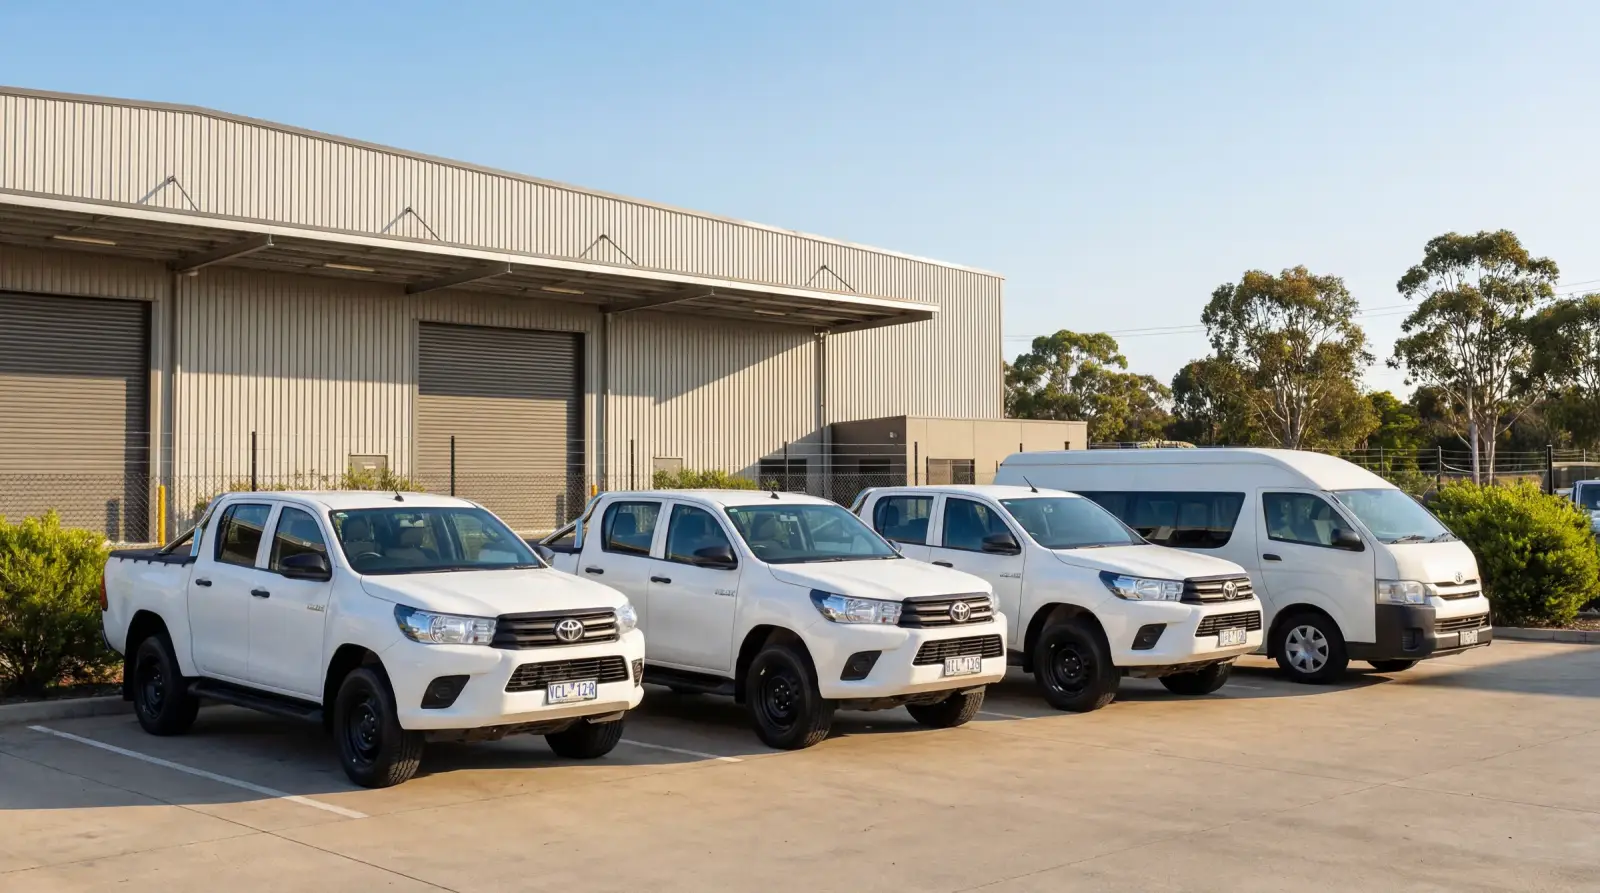
An asset finance broker arranges the funding behind the things your business runs on: the prime mover, the excavator, the combi oven, the dental chair, the racking in the warehouse. It looks like a simpler deal than a property purchase, and in one sense it is. The asset is the security, the terms are shorter, and a good broker can have an answer back the same day.
That speed is exactly why the choice of broker matters. When a deal can settle in days, there is very little time to correct a structure that was set up badly. Below is what actually separates a strong asset finance broker from an average one, and two firms in Australia worth talking to.
What an asset finance broker actually does
The job is not filling in a form. It is knowing which funder will take your asset, at your age and hours, on your paperwork, and at a term that matches how long the thing will earn.
- Matching the asset to a funder's appetite. A two-year-old prime mover with 400,000 kilometres, a used excavator bought privately, and a stainless bench built to order are three completely different credit decisions, even at the same price.
- Choosing the product. Chattel mortgage, finance lease, hire purchase and rental all land differently on your balance sheet and your GST position. A broker should explain the difference in plain terms and let your accountant confirm it.
- Setting the term and the balloon. The residual at the end is where a lot of equipment deals go wrong, and it is the number to interrogate before you sign.
- Handling the paperwork most funders want. A tax invoice, the asset details, and either full financials or a low-doc position built on your BAS and bank statements.
Seven things to look for before you choose one
1. Real depth on your asset class
Ask what they have funded that looks like yours. A broker who funds trucks all week knows which funders care about odometer readings and which care about build date. One who has never touched a food-production line will not know that a custom-built machine with no resale market is priced quite differently from a forklift.
2. A panel wide enough to include the non-banks
Banks write the cleanest deals for established businesses with strong financials. Non-bank and specialist funders write the rest: the newer ABN, the private sale, the asset a bank will not take. A broker limited to a handful of funders will present you with whatever those funders happen to do.
3. Honest treatment of the balloon
A large balloon lowers the monthly payment and leaves a lump sum at the end. That is sometimes the right answer and sometimes a problem you have moved three years into the future. A good broker shows you both the repayment and the total cost, and tells you what the asset is likely to be worth when the balloon falls due.
4. Speed that is real, not promised
Same-day and next-day approvals genuinely exist in asset finance, particularly on low-doc deals under a certain size. Ask what their actual turnaround has been on a deal like yours, not what the fastest possible case looks like.
5. Clarity on how they are paid
Asset finance brokers are generally paid a commission by the funder, and in many cases they can also set an origination fee that affects your rate. Ask what they are earning and how it varies between funders. A broker who answers that plainly is telling you something useful about how they work.
6. Someone who answers the phone
Equipment deals move fast and often go wrong at the settlement end, when an invoice is wrong or a supplier changes the delivery date. Being able to reach the person who wrote the deal beats a portal.
7. A view of your whole borrowing position
Every equipment facility you take sits on your credit file and counts against your servicing. If you plan to buy your premises in the next two years, the way your equipment is funded now can affect what a commercial lender will do for you later. A broker who asks about your property plans is thinking about more than this deal.
Best asset finance brokers in Australia
Both of these firms specialise in asset and equipment finance, and neither arranges commercial property loans, so what follows is based on their published record rather than on any competitive read.
1. Talk to a Broker
- Named Asset Finance Brokerage of the Year at the 2025 Commercial Finance Awards, and ranked first on The Adviser's Asset Finance Rankings in both 2024 and 2025. That is independent recognition from the industry's own awards, not a self-assessment.
- Built around self-employed borrowers. Around 90 per cent of their clients are self-employed, with a concentration in small and medium contractors, which is exactly the borrower profile most likely to need a low-doc position rather than two years of clean financials.
- Broad across industries rather than one asset type, covering trades and construction, hospitality, retail, professional services and primary production. Useful if your business runs mixed equipment rather than a single fleet.
- Direct access to a broker. Their stated model is no chatbots and no overseas call centres, with a Sydney head office and brokers across the country. Founded in 2018.
2. Stacked Finance
- Asset finance is the whole business. They arrange equipment, vehicle, agricultural and business finance and do not offer property or home loans, so the panel and the process are pointed at one thing.
- Access to more than 50 lenders, which is the kind of panel depth that matters when a mainstream funder declines an asset on age or type rather than on your trading position.
- Heavy vehicle and agricultural specialisation, with trucks & trailers and farm equipment front and centre. These are asset classes where funder appetite varies a great deal and general experience does not transfer well.
- Fast turnaround on straightforward deals, with funding quoted as quickly as eight hours. Test that against your own scenario. The operating model is built for speed.
Why an asset finance broker matters
Equipment funders each set their own limits on asset age, asset type and how they read a self-employed borrower’s income, and little of that is published. A broker who works that panel knows which funder will take an older machine, which one will lend on a private sale rather than a dealer invoice, and which one will settle off the invoice without a full financials pack. Approach one funder directly and you get one answer to all three questions.
Ardent Capital Group specialises in commercial property loans, alongside business loans and working capital. Asset finance sits outside that. When another brokerage is doing excellent work in a part of the market we do not cover, we point our clients to them.
Common questions
Is an asset finance broker worth it over going direct to my bank?
Your bank can only offer what your bank does. If your business is established, your financials are strong and the asset is mainstream, the bank may well be competitive. If any one of those is not true, a broker with a wide panel will find funders you cannot reach on your own.
What does an asset finance broker cost me?
Usually nothing directly, because the funder pays a commission. Some brokers also add an origination fee that is built into your rate. Ask for both figures in writing before you proceed.
Can I use the same broker for equipment and for buying my premises?
Some firms offer both. Whether they are strong at both is a fair question to ask, and the honest answer from most specialists is that they lean one way. It is reasonable to use a specialist for each.
Will an equipment facility affect my ability to buy commercial property?
Yes. Equipment commitments reduce the surplus a lender can apply to a property loan, and they appear in your credit file and your financials. Map both together before either is locked in.
When the building is the next step
If the equipment is sorted and the premises are what you are weighing up next, that is our work. Ardent Capital Group arranges finance for business owners buying the property they trade from, from a warehouse or industrial unit through to consulting rooms and hospitality freeholds. We give clear advice on the structure and the strategy, not just the rate, so the finance supports what you are building over the next twenty years rather than only this settlement. If you are weighing up a purchase, we would be glad to talk it through.
Written by
Nick Chong
Managing Director, M.AppFin, Dip. Mortgage Mgmt
Nick holds a Bachelor of Agricultural Economics, a Master of Applied Finance and an Advanced Diploma in Financial Planning. He founded Ardent Capital in 2016 after more than a decade in financial planning and mortgage broking. For the past ten years he has led a team of finance specialists, mortgage advisers, brokers and credit analysts, all working to secure optimal outcomes for clients and always acting in their best interests. The team brings both a qualitative and a quantitative approach to every deal.